A bank deduction from a freelance payment may be final tax in some qualifying export cases, but you should never assume that from the percentage alone. The answer depends on what the payment was for, which legal section the bank used, whether you meet the relevant conditions, your PSEB and filer status, and whether the deduction was actually connected with the remittance.
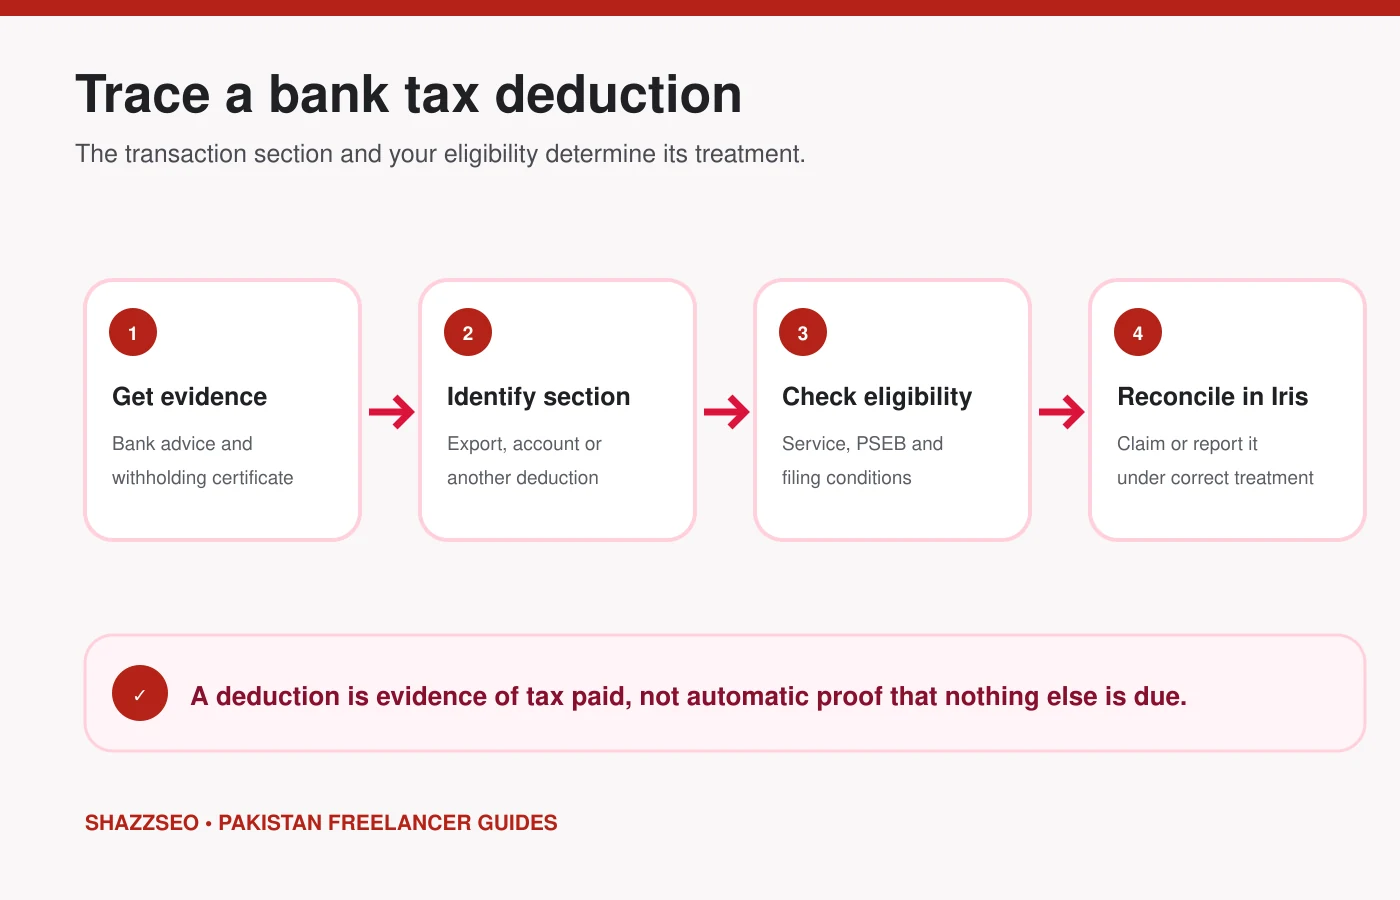
Your first task is not to calculate more tax. It is to identify the deduction using the bank advice or withholding certificate.
Why banks deduct tax from freelancer payments
Pakistani banks act as withholding or collection agents for several types of transactions. A deduction visible near a foreign remittance could relate to export proceeds, account profit, cash withdrawal, card use, a bank fee with tax, or another transaction. The posting date alone does not prove its purpose.
The current FBR withholding-tax rate cards should be checked for the relevant tax year. FBR’s payment classifications have separately identified export of IT and IT-enabled services under section 154A at 0.25% and other export of services under section 154A at 1%, subject to the governing law and eligibility conditions. Do not apply either rate merely because you use Fiverr or Upwork.
When can the 0.25% rate apply?
The concessionary rate is associated with qualifying exports of computer software, IT services or IT-enabled services by an exporter registered and certified with PSEB, together with the conditions in section 154A. Your work must fit the eligible service classification, export proceeds must be properly realized and documented, and applicable compliance conditions must be met.
A graphic designer, marketer, consultant or writer should not automatically describe all work as IT or ITeS. The actual service and current classification control the treatment. Review our PSEB registration guide, then confirm eligibility rather than choosing a favorable label.
Final tax, minimum tax and adjustable tax
These terms have different results:
- Final tax: the deduction can represent the tax on the covered income when all statutory conditions are met.
- Minimum tax: the amount is a floor, and the final computation may produce a higher liability.
- Adjustable or advance tax: the amount is credited against the tax calculated in your return.
Finance Acts can change a deduction from one category to another. Section 154A service-export treatment should not be confused with section 154 treatment for other export proceeds or with ordinary business income. Use the current tax year’s law and rate card.
How to identify what the bank deducted
1. Download the complete statement
Check the payment credit and every separate debit posted around it. Note the date, amount, narration, transaction ID and resulting balance.
2. Ask for a withholding certificate
Request a certificate or official advice that states the tax section, taxable base, rate and amount. A branch employee’s verbal explanation is not enough for your annual file.
3. Check the remittance purpose
Confirm how the bank classified the receipt and whether the ePRC or credit advice reflects the actual service. An incorrect home-remittance or generic purpose may create a mismatch even if money reached your account.
4. Compare the deduction with the gross base
Calculate the effective rate: tax deducted divided by the amount on which the bank says it applied tax. Do not divide by the PKR bank credit if platform fees and conversion occurred earlier.
Example: why the visible percentage can mislead you
A client pays USD 2,000. A platform deducts USD 200, a payment provider deducts USD 20, and the Pakistani bank receives the equivalent of USD 1,780. If the bank withholds tax from the realized export amount, dividing that tax by the original USD 2,000 may show a percentage different from the statutory rate.
Build a bridge containing gross client payment, platform fee, payment-provider fee, remitted amount, bank conversion, bank charges and tax deduction. That bridge lets a tax adviser determine whether the base was correct.
Is the bank deduction your final tax?
It may be if the payment is qualifying export income under the correct final-tax provision and you have met every required condition. It may not be final if:
- The work does not qualify as the service category used.
- Your PSEB registration or certification was absent or invalid where required.
- The payment was local income rather than export proceeds.
- The bank used a different withholding section.
- The tax is adjustable, advance or minimum tax under the applicable rule.
- You have other freelance, salary, business, property or investment income.
- The rate or transaction base was incorrect.
Even when the deduction is final for that stream, you normally still need to file the return and wealth statement when legally required. Final tax does not mean “do not disclose the income.”
What to do if the rate appears wrong
- Collect the invoice, platform statement, withdrawal record, bank advice and withholding certificate.
- Verify your PSEB status and service classification for the payment date.
- Ask the bank’s remittance or tax team to explain the section and base in writing.
- If the purpose code is wrong, request the bank’s correction process.
- Do not ask the bank to alter a genuine transaction description merely to obtain a lower rate.
- Give the evidence to your tax professional before filing or revising the return.
How to reconcile the deduction in Iris
Check whether the withholding appears in your tax records and whether its section and amount match the certificate. Enter or claim it only under the correct treatment. Keep the original certificate because an automatically populated figure can still be incomplete or incorrectly categorized.
If an amount is missing, use the lawful correction or evidence process rather than adding an unsupported tax credit. FBR’s official return-filing guidance directs taxpayers to file through Iris.
Common mistakes
- Assuming every foreign payment is an IT export.
- Treating platform fees as tax deducted by a Pakistani bank.
- Using PSEB registration obtained after the period without checking applicability.
- Declaring only the net bank credit and losing the gross-to-net trail.
- Assuming “final tax” means no return or wealth statement.
- Claiming a deduction twice when it appears automatically in Iris.
Frequently asked questions
Does every freelancer qualify for 0.25%?
No. The concession applies to qualifying IT and ITeS exports with the required PSEB and legal conditions. Platform membership alone is not eligibility.
What if the bank deducted 1%?
One percent may correspond to another service-export classification, an ineligible 0.25% claim or a bank classification issue. Obtain the section and certificate before concluding which one.
Can I claim a refund?
A refund depends on whether the amount is legally refundable or adjustable and on your overall return. Final tax is not handled like ordinary adjustable withholding. Seek advice before making a claim.
Does Payoneer deduct Pakistani income tax?
Payoneer and platforms charge fees and may apply deductions under their own rules. Identify the issuer of every deduction. Do not label a platform fee as FBR tax.
Should I change banks?
First determine whether the problem is the law, your documentation or an operational classification. If a bank repeatedly cannot provide ePRCs, certificates or competent remittance support, compare the bank accounts available to Pakistani freelancers.
Bottom line
A bank tax deduction can be final for a qualifying income stream, but the bank statement alone cannot answer the question. Identify the legal section, taxable base, service category and your eligibility, then reconcile the certificate in Iris. Keep the complete payment trail for every material remittance.
This guide is general educational information, not individualized tax advice. Verify the applicable Finance Act, FBR rate card, PSEB status and transaction treatment with FBR or a qualified Pakistani tax professional.