If money remains in your Payoneer account at the end of the Pakistani tax year, do not leave it out merely because it has not reached your local bank. The closing balance is generally an asset that should be considered in your wealth disclosure. The related freelance earnings must also be reported under the correct income treatment. The balance and the income are connected, but they are not the same entry.
This guide shows Pakistani freelancers how to prepare a defensible Payoneer figure for an FBR wealth statement. It does not assume one fixed Iris field because FBR can revise return forms, labels and validation rules between tax years.
Why a Payoneer balance matters to FBR
A wealth statement is a statement of your assets and liabilities at the relevant year end. Money held in a payment account does not disappear from your wealth merely because it has not been withdrawn to Pakistan. If you can access or control the balance, it may need to be included among your assets.
FBR’s Iris portal is used for income-tax returns and wealth statements. FBR also has a separate foreign income and assets statement requirement under section 116A for resident individuals who meet the statutory foreign-income or foreign-asset thresholds. A Payoneer balance can therefore affect more than one disclosure question.
Income, withdrawals and balance are different
Item |
What it tells you |
Common mistake |
|---|---|---|
Platform earnings |
Value earned through Fiverr, Upwork or direct clients |
Reporting only what reached the bank |
Payoneer withdrawal |
Movement from Payoneer to a bank or wallet |
Counting the transfer as new income again |
Payoneer closing balance |
Amount still held at the reporting date |
Omitting it because it is outside a Pakistani bank |
Platform and payment fees |
Difference between gross earnings and available cash |
Ignoring why the figures do not match |
Moving your own money from Payoneer to a Pakistani bank normally changes the location of an asset. It does not automatically create income a second time. Your tax treatment still depends on when the underlying income is recognized and which accounting method and tax regime apply to you.
Documents to download before opening Iris
- Payoneer statement covering July 1 through June 30.
- A statement or screen showing the exact closing balance in each currency.
- Fiverr, Upwork or client earnings reports.
- Withdrawal confirmations and transaction IDs.
- Pakistani bank statements showing amounts received.
- Invoices, contracts and material refund records.
- Platform fees and Payoneer charges.
- Your prior-year wealth statement and prior Payoneer closing balance.
Keep original CSV or PDF reports. Screenshots are useful only when an original downloadable report does not preserve the required information.
How to calculate the Payoneer closing balance
1. Use June 30 as the normal tax-year cut-off
Pakistan’s normal tax year ends on June 30. Use the actual available balance at the end of that date, not today’s balance and not the amount withdrawn during September when you file.
2. Separate each currency
Record USD, GBP, EUR and other balances separately before conversion. This leaves an audit trail and prevents an unexplained blended exchange rate.
3. Include funds you control
Use the amount available to you at year end. If a payment was pending, reserved, disputed or not yet released, retain evidence of its status and ask your tax professional whether it belonged in receivables, platform balance or neither at that date.
4. Convert the balance into PKR consistently
Iris requires PKR figures. Use a reasonable, supportable exchange-rate method consistently and save its source and date. Do not choose whichever rate produces the lowest closing wealth. Your adviser may use the year-end rate or another method required by the applicable return and accounting basis.
A practical reconciliation example
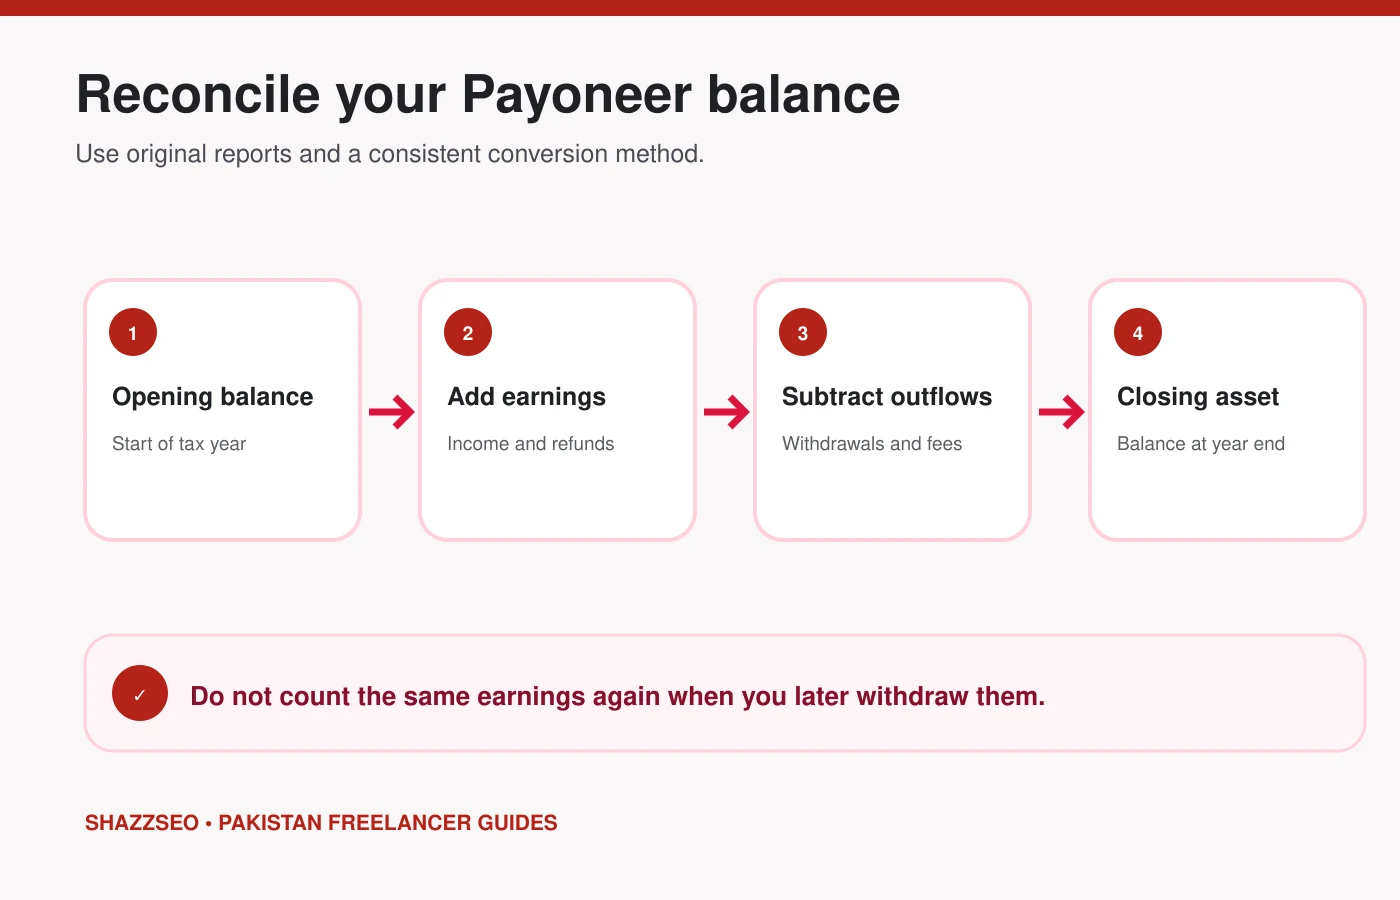
Assume your opening Payoneer balance was USD 500. During the tax year, USD 8,000 became available, USD 6,500 was withdrawn, and USD 200 was deducted as fees or adjustments.
- Opening balance: USD 500
- Add available earnings and other credits: USD 8,000
- Less withdrawals: USD 6,500
- Less fees and adjustments: USD 200
- Expected closing balance: USD 1,800
The USD 1,800 should match Payoneer’s closing record. Convert that asset into PKR for the wealth statement. Separately, reconcile the income figure using the correct gross earnings, fees and tax treatment. A USD 6,500 withdrawal should not be added as another USD 6,500 of income if the underlying earnings were already recognized.
Where should it be entered in Iris?
The exact field depends on the tax year’s Iris form and professional interpretation of the account. It may appear under foreign assets, financial assets, bank or account balances, or another appropriate asset category. Do not force the amount into “cash in hand” simply because it is easy to find.
Use a clear description such as “Payoneer closing balance” and keep the account identifier masked in your working papers. If your adviser treats the Payoneer account as a foreign financial asset, use that treatment consistently across the wealth statement and any required foreign income and assets statement.
Do you also need a section 116A statement?
Section 116A applies to a resident individual with foreign income of at least USD 10,000 during the tax year or foreign assets valued at USD 100,000 or more at the end of the tax year. The Commissioner can also require information in circumstances allowed by law.
Those thresholds do not mean smaller foreign balances should automatically be omitted from the ordinary wealth statement. They determine whether the additional foreign income and assets statement requirement applies. Confirm whether platform income and the location of your Payoneer account fall within your case.
How the balance affects wealth reconciliation
A wealth reconciliation explains the movement from last year’s net wealth to this year’s net wealth. If your Payoneer asset increased by PKR 400,000, the reconciliation should show a credible source, normally declared income or another documented transfer, after considering expenses and other asset movements.
If Iris reports an unreconciled difference, do not insert a fake gift, loan or personal expense to make the validation pass. Return to the opening balance, income, withdrawals, bank assets, fees, personal expenses and closing balance.
Common mistakes to avoid
- Declaring only money withdrawn to a Pakistani bank.
- Counting the same income when earned and again when withdrawn.
- Using today’s Payoneer balance instead of the June 30 balance.
- Ignoring balances held in a second currency.
- Mixing Payoneer funds with the related Pakistani bank asset after transfer.
- Reporting a net amount without preserving gross earnings and fee records.
- Copying last year’s figure without checking this year’s statement.
Frequently asked questions
Is an unwithdrawn Payoneer balance taxable?
The tax point depends on the underlying income, availability of funds, accounting basis and applicable regime. “Not withdrawn” does not automatically mean “not reportable.” Obtain advice for material balances.
Should Payoneer be shown as cash in hand?
Usually it is better treated according to its true nature as an account or financial balance rather than physical cash. Use the most appropriate field available in the current Iris form.
What if the Payoneer and bank amounts differ?
Prepare a bridge for fees, currency conversion, pending transfers and timing. The statement, withdrawal record and bank credit should explain the difference.
Can I revise a wealth statement?
FBR explains that a wealth statement can be revised in Iris before the relevant notice under section 122(9), subject to the applicable rules. Use the official process rather than submitting random replacement figures.
Do I need an accountant?
A modest single-currency balance may be straightforward. Professional review is sensible when you have large balances, several platforms, foreign bank accounts, prior omissions, section 116A exposure or an unreconciled wealth difference.
Final checklist
Save the June 30 balance, convert it consistently, disclose it in a suitable asset field, report the related income correctly, and reconcile withdrawals without double counting. If you are still preparing your return, use our broader guide on filing an income-tax return in Pakistan.
This article provides general educational information, not individualized tax or legal advice. Iris forms and tax treatment change. Verify the current return, Finance Act and your facts with FBR or a qualified Pakistani tax professional.